Live Webinar
Basic Payroll 101
- 2.00 CPE (Continuing Professional Education)
- 1.50 HRCI (Human Resource Certification Institute)
- 1.50 SHRM (Society for Human Resource Management)
- 1.50 RCH (American Payroll Association)
- 1.50 ATATX (Aurora Accounting)
- 1.50 ATAHR (Aurora HR)
- 0.75 ATAPR (Aurora Payroll)
What You'll Learn
- The type of payroll frequency used by the employer
- The information supplied on the employee’s Form W-4
- The taxable wage base and rate in effect for OASDI or social security taxes
- The rate in effect for Medicare tax
- If the employee is subject to the Additional Medicare Tax
- Status of the employees such as nonresident alien or expatriate
- The wage base and rate in effect for federal unemployment insurance or FUTA
View Full Description
Background:
Federal income taxes are such a common occurrence in present times it is easy to forget their relatively recent origin. It is also easy to forget that the withholding of these taxes fall under IRS regulations that are strict and non-yielding in many cases. Simply put, the employer either collects the amount due from the employee or pays their own portion and sends it directly to the IRS. But though it sounds simple and basic it is critical for the employer to withholding the taxes correctly based on several factors including:
The penalties are severe for failing to comply with employment tax rules and procedures since the IRS imposes both civil and criminal penalties on employers. In addition to these penalties, employers also have to pay interest on any underpayment of tax that is a result of noncompliance with these same regulations.
Then once the taxes are withheld and paid they must be reported and reconciled. Which forms are used for the initial reporting and when are they due? Which forms are used to correct already submitted forms? These are critical questions that the payroll professional must have answers to right on the tip of their tongues. So although we like to refer to this as basic payroll it is anything but basic. In actuality it is the foundation that supports both quarter-end and year-end as well as all other IRS compliance issues facing the payroll department.
Your Benefits For Attending:
- Introduction to the federal tax system
- Obtaining an EIN
- Federal Income Tax
- Methods of withholding
- How to handle supplemental wages
- FICA Taxes
- What is OASDI
- What is Medicare
- What is the Additional Medicare Tax
- What are the current wage bases and rates
- How do totalization agreements affect FICA taxes
- Are there special rules for nonresident aliens on visa
- FUTA Tax
- Who is subject
- Current rate and wage base
- Effect of credit reduction
- Computing and paying the tax
- Who is subject
- Basic rules for Successor employers
- Basic rules for Common Paymaster
- Deposit rules
- Reporting requirements
- Penalties for noncompliance
Who Can Benefit:
- Payroll Executives/Managers/Administrators/Professionals/Practitioners/Entry Level Personnel
- Human Resources Executives/Managers/Administrators
- Accounting Personnel
- Business Owners/Executive Officers/Operations and Departmental Managers
- Lawmakers
- Attorneys/Legal Professionals
- Any individual or entity that must deal with the complexities and requirements of Payroll compliance issues
Meet Your Speaker
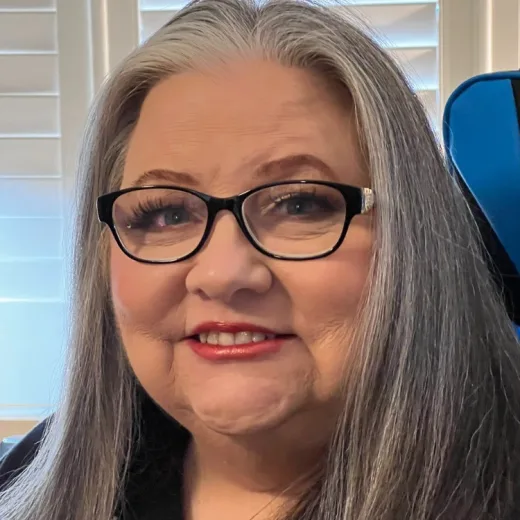
Vicki M. Lambert, CPP
Vicki M. Lambert, CPP, is President and Academic Director of The Payroll Advisor™, a firm specializing in payroll education and training. The company offers a payroll news service which keeps payroll professionals up-to-date on the latest rules and regulations.With over 35 years of hands-on...
View Full Bio of Vicki M. Lambert, CPPWhat Attendees Are Saying
-
“This was a very informative session. Several questions I had were answered in the presentation. ”
-
“I wish so much time wasn't given to the backside of figuring out taxes. That's good to know, but it was too in depth when...”
-
“Vicki Lambert is fantastic presenter, her knowledge and humor are the best!”
-
“It was very helpful but it was more payroll tax oriented than payroll oriented. I realize you can't cover all of payroll...”
See the survey ratings
5 attendees rated this webinar 4.2 out of 5 on average.
Webinar Presentation
- How many of the objectives of the event were met?
- 4.4
- How useful was the information presented at this event?
- 3.8
- Overall, how satisfied were you with this event?
- 3.8
Speaker Performance
- Overall, how satisfied were you with this presenter?
- 4.6
- How closely did the presenter follow the schedule?
- 4.4
CE Credits
These are the continuing education credits available to you for this webinar.
- 2.00 CPE
 Continuing Professional Education
Aurora Training Advantage is registered with the National Association of State Boards of Accountancy (NASBA) as a sponsor of continuing professional education on the National Registry of CPE Sponsors. State boards of accountancy have final authority on the acceptance of individual courses for CPE credit. Complaints regarding registered sponsors may be submitted to the National Registry of CPE Sponsors through its website: www.nasbaregistry.org.
For more information regarding administrative policies such as complaint and refund, and cancellation please contact our offices at 407-542-4317 or [email protected].
- 1.50 HRCI
 Human Resource Certification Institute Browse HRCI-approved webinars and earn recertification credits online. Live and on-demand HR training for PHR, SPHR, and GPHR recertification. Expert-led sessions from Aurora Training Advantage.
- 1.50 SHRM
 Society for Human Resource Management Aurora Training Advantage is recognized by SHRM to offer Professional Development Credits (PDCs) for the SHRM-CPSM or SHRM-SCPSM. For more information about certification or recertification, please visit www.shrmcertification.org.
- 1.50 RCH
 American Payroll Association
Aurora Training Advantage is an approved provider through the American Payroll Association. To receive credit through the American Payroll Association for this program you MUST attend the program in its entirety.
- 1.50 ATATX Aurora Accounting Aurora Training Advantage is offering continuing education points designed to recognize dedication to training and excellence in accounting.
- 1.50 ATAHR Aurora HR Aurora Training Advantage is offering continuing education points designed to recognize dedication to training and excellence in human resources.
- 0.75 ATAPR Aurora Payroll Aurora Training Advantage is offering continuing education points designed to recognize dedication to training and excellence in payroll.