Form 1099 Update
Access this expert-led webinar instantly, available anytime on-demand.
Included in All-Access Membership
With constant revisions to Form 1099 and the related reporting rules, staying up to date with the latest compliance requirements is essential to avoid costly penalties, interest charges, and the time-consuming task of correcting errors. This webinar is designed to provide the most current and comprehensive guidance on information reporting, particularly focusing on the changes brought about by Forms 1099-NEC and 1099-MISC. Whether you're handling reporting for a business, nonprofit, or professional firm, this session offers the clarity and direction you need to remain compliant and efficient.
You'll learn how to accurately report various payment types, avoid the most common filing mistakes, and determine which forms apply to specific situations—including payments to attorneys and healthcare providers, goods and services, and rental property. This session will also cover the proper handling of payments to corporations and LLCs, information reporting to nonprofits, and other tricky classification scenarios. In addition, you’ll gain valuable strategies for establishing compliant internal policies and procedures to ensure your organization is audit-ready.
Everything you need to know to prepare the Latest 1099 Forms:- Changes to Forms 1099 and what information you need to be in compliance
- What to do if payments include both goods and services
- Rentals of personal property vs rentals of real property
- Payments to Attorneys & Health Care Professionals
- Judgment Payments and Forms 1099
- What is reportable and which Form 1099 to use
- Information reporting to non-profits
- Information reporting to Corporations, LLCs & other tricky classifications
- Updates on various 1099 forms and their respective reporting requirements
- Determine which form to use and what amounts are reportable
- Overview of latest penalty increases for noncompliance and possible abatement of penalties
- Tips for developing information reporting office procedures which reflect due diligence on the part of the payer
Attending this webinar will arm you with the up-to-date knowledge and practical tools you need to confidently handle your year-end information reporting. Whether you're aiming to prevent penalties or improve efficiency, this session offers clear value to any professional involved in 1099 compliance.
Who Would Benefit from this Webinar:- Accountants and bookkeepers responsible for year-end reporting
- Tax professionals and advisors preparing 1099 forms
- Payroll managers and HR professionals involved in vendor payments
- Business owners who manage payments to contractors, vendors, or professionals
- Nonprofit administrators handling grant or service payments
Instructional Delivery Method: Group Internet Based
Delivery Format: Live Webcast
NASBA Field of Study: Taxes (2 hours)
Program Prerequisites: None
Advance Preparation: No
- Introduction
- The Law – Learn It, Know It, Live It 00:01:07
- What's New in 1099 E-Filing 00:07:26
- What's New in 1099 E-Filing – IRIS A2A Connection and State Reporting 00:14:46
- New 2026 Form 1099-NEC 00:25:43
- New 2026 Form 1099-MISC 00:35:07
- 1099-MISC Box One – Rent 00:37:18
- 1099-MISC Box One – Form 1099-S and Hotels 00:39:11
- 1099-MISC Box Two – Extractive Industries 00:42:06
- 1099-MISC Box Two – Creative Industries 00:43:54
- 1099-MISC Box Two – Intellectual Property 00:46:31
- 1099-MISC Box Two – Royalty Reporting Chart 00:48:39
- 1099-MISC Box Three – Prizes, Awards and Death Payments 00:49:20
- 1099-MISC Box Three – Settlement Payments 00:49:53
- 1099-MISC Box Four – Backup Withholding 00:52:30
- 1099-MISC Box Six – Medical Payments 00:54:07
- 1099-MISC Box Six – Medical Services and Products 00:55:03
- 1099-MISC Box Six – Reporting Exceptions 00:57:05
- 1099-MISC Box Ten – Legal Services 00:57:30
- 1099-MISC Director's Payments 00:58:00
- 1099-MISC/NEC Threshold Summary in Review 00:59:07
- 1099-K Update 01:01:36
- 1099-R Update 01:04:25
- 1099-INT Update 01:05:26
- 1099-DA Update 01:05:53
- 1099-B/DIV Update 01:06:52
- 1099-C Update 01:08:13
- Proposed W-9 Changes 01:09:53
- Name and TIN Cheat Sheet – Individuals and Sole Proprietors 01:11:43
- Name and TIN Cheat Sheet – Business Entities 01:13:38
- Validating W-9 Data – Updated Forms and Solicitation 01:15:45
- Validating W-9 Data – Corporations 01:18:22
- Validating W-9 Data – LLCs 01:18:52
- Validating W-9 Data – Disregarded Entities 01:19:27
- Validating W-9 Data – Tax-Exempt Organizations 01:20:21
- TIN Match Program – Overview 01:20:49
- TIN Match Program – Authorized Users 01:21:40
- Validating W-9 Data: Watch Out for the Middleman 01:22:18
- Backup Withholding Tips 01:24:25
- B-Notice Response Best Practices – CP2100 Notices 01:25:03
- B-Notice Response Best Practices – Name and TIN Mismatches 01:26:29
- B-Notice Response Best Practices – First Notice 01:28:43
- B-Notice Response Best Practices – Second Notice 01:30:15
- IRS Form 972-CG Proposed Penalty Notice and Reasonable Cause 01:32:49
- IRS Form 972-CG – Notice Contents and Response 01:33:32
- IRS Form 972-CG – Responding to Proposed Penalties 01:34:20
- IRS Form 972-CG – Proving Reasonable Cause 01:34:51
- IRS Form 972-CG – Preparing a Penalty Waiver Request 01:35:07
- IRS Form 972-CG – Supporting Documentation 01:36:00
- Questions and Answers 01:39:44
- Closing Remarks 01:43:53
-
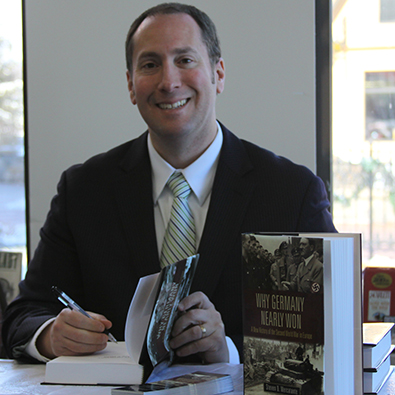
Steven Mercatante
Steven Mercatante is the principal and founder of TIR Consulting, LLC. He is a nationally recognized leader in tax reporting education and consulting on specialized compliance issues. He has conducted on-site consultation for corporate clients from across the world and led countless seminars and web [...]
ATATX Credit
Aurora Training Advantage is offering continuing education points designed to recognize dedication to training and excellence in accounting.CPE Credit

Aurora Training Advantage is registered with the National Association of State Boards of Accountancy (NASBA) as a sponsor of continuing professional education on the National Registry of CPE Sponsors. State boards of accountancy have final authority on the acceptance of individual courses for CPE credit. Complaints regarding registered sponsors may be submitted to the National Registry of CPE Sponsors through its website: www.nasbaregistry.org.
For more information regarding administrative policies such as complaint and refund, and cancellation please contact our offices at 407-542-4317 or [email protected].
You must answer all questions during the webinar, view the recording completely and pass the test at the end with 70% correct answers to receive CPE credit.
IRS Credit
Browse previous versions of this webinar series:
- Form 1099 UpdateWebinar Date: October 6, 2026VIEWING
- Form 1099 UpdateWebinar Date: September 17, 2025
- Accountable Plan 01:15:46
- Artificial Intelligence (AI) 00:02:39, 00:02:46, 00:02:59, 00:03:08, 00:03:18, 00:03:41, 00:03:50, 00:04:09, 00:04:09, 00:04:09, 00:05:08, 00:41:27, 00:41:54, 00:54:49
- Audit 00:02:08, 00:02:51, 00:29:47, 00:30:22, 00:34:11, 00:34:11, 00:47:46, 00:58:07, 01:24:36, 01:24:45, 01:24:45
- B-Notice 01:25:03, 01:25:03, 01:25:09, 01:25:51, 01:27:28, 01:27:34, 01:28:43, 01:31:12, 01:31:30, 01:33:10, 01:33:25
- Backup Withholding 00:02:08, 00:05:28, 00:27:17, 00:52:30, 00:59:59, 01:09:36
- CP-2100 01:25:13, 01:27:02, 01:27:40, 01:27:52, 01:28:16, 01:28:43
- DBA – Doing Business As 01:13:55, 01:26:47
- Disregarded Entity 01:11:15, 01:11:15, 01:12:29, 01:13:55
- EIN 01:10:59, 01:11:15, 01:12:01, 01:12:12, 01:12:29, 01:17:10, 01:17:25, 01:26:47, 01:41:33, 01:41:59, 01:41:59
- Exempt 00:57:09, 01:20:12, 01:20:19, 01:20:19, 01:20:38
- Expense 00:44:26, 00:50:19
- Expense Reimbursement 00:50:19
- Fair Labor Standards Act (FLSA) 00:32:51, 00:34:29, 00:34:29
- FIRE – File Information Returns Electronically 00:07:53, 00:08:08, 00:09:21, 00:09:29, 00:09:46, 00:12:25, 00:16:17, 00:17:25, 00:18:05, 00:18:25, 00:19:05, 00:19:29, 00:19:33, 00:19:33, 00:19:48, 00:20:00, 00:20:48, 00:21:59, 00:22:33, 01:40:18
- Form 1042-S 00:08:40
- Form 1099-B 01:06:52
- Form 1099-C 01:08:13, 01:08:39
- Form 1099-DA 00:08:40, 01:05:53, 01:06:25, 01:06:37
- Form 1099-DIV 01:07:23, 01:08:02
- Form 1099-INT 01:05:37
- Form 1099-K 01:01:36, 01:01:50, 01:02:00, 01:03:54
- Form 1099-MISC 00:11:10, 00:24:07, 00:25:52, 00:26:24, 00:28:48, 00:35:07, 00:35:07, 00:37:18, 00:38:30, 00:40:06, 00:40:37, 00:42:06, 00:42:34, 00:43:25, 00:49:20, 00:51:10, 00:52:30, 00:53:41, 00:57:37, 00:58:03, 00:59:19, 01:23:40, 01:41:04, 01:42:56, 01:43:22
- Form 1099-NEC 00:11:10, 00:23:15, 00:24:20, 00:25:52, 00:26:24, 00:26:41, 00:28:48, 00:35:19, 00:40:29, 00:43:28, 00:44:59, 00:47:26, 00:48:50, 00:50:51, 00:52:30, 00:54:15, 00:58:17, 00:59:19
- Form 1099-R 01:04:25
- Form 1099-S 00:39:11, 00:39:22, 00:39:40, 00:40:06, 00:43:45
- Form 8809 00:24:00
- Form W-2 00:24:20, 00:52:14, 01:41:06
- Form W-9 00:04:37, 00:05:57, 00:06:08, 00:53:02, 01:08:55, 01:08:59, 01:09:48, 01:09:53, 01:10:17, 01:10:51, 01:11:15, 01:11:48, 01:11:48, 01:12:12, 01:12:54, 01:12:54, 01:13:26, 01:15:53, 01:16:14, 01:18:14, 01:18:34, 01:19:58, 01:28:43, 01:28:43, 01:29:53, 01:31:12, 01:31:27, 01:31:30, 01:36:00
- Gross Proceeds Payment 00:59:19, 01:06:14
- Independent Contractor 00:26:24, 00:30:43, 00:31:49, 00:32:31, 00:33:43, 00:34:11, 00:53:02, 01:06:37, 01:08:13, 01:20:42, 01:25:29, 01:25:41, 01:25:51, 01:26:20
- Information Returns Intake System (IRIS) 00:07:36, 00:07:36, 00:07:36, 00:07:53, 00:07:53, 00:08:08, 00:08:08, 00:09:02, 00:09:21, 00:09:29, 00:09:41, 00:10:03, 00:12:17, 00:13:15, 00:14:46, 00:14:50, 00:16:46, 00:17:25, 00:17:25, 00:18:05, 00:18:17, 00:18:25, 00:18:38, 00:19:56, 00:20:34, 00:21:48, 00:21:59, 00:21:59, 00:22:33, 00:36:59, 01:41:18, 01:41:22
- Intangible Personal Property 00:46:31
- Intellectual Property (IP) 00:46:31, 00:46:31, 00:48:50
- IRC Section 409A 00:58:38, 00:58:54
- IRC Section 6045 00:57:57
- IRS Notice 972CG 01:32:54, 01:34:10
- Limited Liability Company (LLC) 00:00:13, 00:33:43, 00:38:40, 01:11:15, 01:12:01, 01:13:55, 01:14:16, 01:14:32, 01:17:25, 01:18:52, 01:18:52, 01:19:01, 01:19:22, 01:19:27, 01:19:31, 01:19:38, 01:26:47, 01:26:47, 01:42:09, 01:42:32, 01:42:46, 01:42:52, 01:42:52
- Nonqualified Deferred Compensation (NQDC) 00:58:54
- Overtime 00:28:48, 00:28:48, 00:29:57, 00:30:25, 00:30:25, 00:32:08, 00:32:31, 00:32:31, 00:32:31, 00:34:44, 00:35:07, 00:35:19, 01:03:34
- Personal Property 00:40:41, 00:46:31
- Real Property 00:39:15, 00:40:45
- Reasonable Cause 00:14:22, 00:30:51, 01:37:46
- Sole Proprietor 01:10:59, 01:11:15, 01:13:55, 01:17:10, 01:26:47
- Tax Exempt Organization Search Tool 01:20:19
- Tax Gap 00:01:35
- TIN 00:53:02, 01:03:45, 01:09:05, 01:09:17, 01:09:17, 01:12:29, 01:12:54, 01:13:45, 01:13:45, 01:14:16, 01:14:36, 01:14:36, 01:16:33, 01:16:33, 01:21:49, 01:25:13, 01:26:29, 01:26:42, 01:29:53, 01:29:53, 01:31:37, 01:36:40, 01:36:40, 01:41:45, 01:41:48, 01:41:59, 01:41:59
- TIN Match Program 01:09:05, 01:31:37
- Transmitter Control Code (TCC) 00:12:17, 00:12:35, 00:13:58, 00:14:26, 00:15:30, 00:16:36, 00:21:48, 01:41:22, 01:43:27, 01:43:36
- Vendor 00:05:57, 00:14:13, 00:14:59, 00:14:59, 00:18:38, 00:18:38, 00:38:40, 00:41:27, 00:54:49, 01:02:00, 01:05:37, 01:08:13, 01:08:59, 01:09:17, 01:09:34, 01:09:36, 01:10:17, 01:11:48, 01:12:29, 01:13:26, 01:16:14, 01:16:59, 01:17:49, 01:20:19, 01:20:53, 01:24:45, 01:26:01, 01:27:21, 01:28:40, 01:29:53, 01:33:32, 01:33:32, 01:36:40, 01:40:24
Accountable Plan: An accountable plan is a plan that follows the Internal Revenue Service (IRS) regulations for reimbursing workers for business expenses in which reimbursement is not counted as income. ... However, these expenses must be business-related to fall under an accountable plan.
Artificial Intelligence (AI): Artificial intelligence is intelligence demonstrated by machines, as opposed to the natural intelligence displayed by humans or animals.
Audit: A formal examination of an organization's or individual's accounts or financial situation
B-Notice: A notice from the IRS stating that one or more tax ID numbers were missing from a 1099 or do not match the IRS records.
Backup Withholding: Backup withholding is the tax that is levied on investment income, at an established tax rate, as the investor withdraws it. Backup withholding helps to ensure that government tax-collecting agencies (such as the IRS or Canada Revenue Agency) will be able to receive income taxes owed to them from investors' earnings. (www.investopedia.com)
CP-2100: It is a notice that tells a payer that he or she may be responsible for backup withholding. It is accompanied by a listing of missing, incorrect, and/or not currently issued payee TINs. Largevolume filers will receive a CD or DVD data file CP2100, mid-size filers receive a paper CP2100, andsmall filers receive a paper CP2100A.
DBA -Doing Business As: Sometimes it makes sense for a company to do business under a different name. To do this, the company has to file what's known as a DBA, meaning "doing business as." A DBA is also known as a "fictitious business name," "trade name," or "assumed name."
Disregarded Entity: A disregarded entity refers to a business entity with one owner that is not recognized for tax purposes as an entity separate from its owner. A single-member LLC ( “SMLLC”), for example, is considered to be a disregarded entity. (www.pntax.com)
EIN: The Employer Identification Number, also known as the Federal Employer Identification Number or the Federal Tax Identification Number, is a unique nine-digit number assigned by the Internal Revenue Service to business entities operating in the United States for the purposes of identification.
Exempt : Exempt employee is a term that refers to a category of employees set out in the Fair Labor Standards Act. They do not receive overtime pay, nor do they qualify for the minimum wage
Expense: Offset (an item of expenditure) as an expense against taxable income.
Expense Reimbursement: Expense reimbursement is a method for paying employees back when they spend their own money on business-related expenses. These expenses generally occur when an employee is traveling for business but can occur in other work-related situations. (www.thebalancecareers.com)
FIRE - File Information Returns Electronically: The IRS FIRE system is the electronic network used to accept and process most types of filing forms. Technically, it stands for File Information Returns Electronically.
Fair Labor Standards Act (FLSA): The Fair Labor Standards Act of 1938 29 U.S.C. § 203 is a United States labor law that creates the right to a minimum wage, and "time-and-a-half" overtime pay when people work over forty hours a week. It also prohibits most employment of minors in "oppressive child labor".
Form 1042-S: Form 1042-S is used to report amounts paid to foreign persons (including persons presumed to be foreign) who are subject to income tax withholding. For an individual taxpayer, Form 1042-S is a document provided to you (and the IRS) by the payer of the income reported.
Form 1099-B: Proceeds From Broker and Barter Exchange Transactions is an Internal Revenue Service (IRS) tax form that is issued by brokers or barter exchanges. The form lists the gains or losses of all broker or barter exchange transactions.
Form 1099-C: According to the IRS, nearly any debt you owe that is canceled, forgiven or discharged becomes taxable income to you. You'll receive a Form 1099-C, "Cancellation of Debt," from the lender that forgave the debt.
Form 1099-DA: This form is specifically designed to handle the reporting for cryptocurrency and digital assets.
Form 1099-DIV : Form 1099-DIV: Dividends and Distributions is an Internal Revenue Service (IRS) form sent to investors who receive distributions from any type of investment during a calendar year. Investors can receive multiple 1099-DIVs. Each Form 1099-DIV should be reported on an investor's tax filing.
Form 1099-INT: Form 1099-INT is the IRS tax form used to report interest income. The form is issued by all payers of interest income to investors at year end and includes a breakdown of all types of interest income and related expenses. Payers must issue Form 1099-INTs for any party to whom they paid at least $10 of interest during the year.
Form 1099-K: A payment settlement entity (PSE) must file Form 1099-K for payments made in settlement of reportable payment transactions for each calendar year. A PSE makes a payment in settlement of a reportable payment transaction, that is, any payment card or third party network transaction, if the PSE submits the instruction to transfer funds to the account of the participating payee to settle the reportable payment transaction.
Form 1099-MISC: The Form 1099-MISC is an Internal Revenue Service (IRS) tax return document used to report miscellaneous payments made to nonemployee individuals, such as independent contractors, during the calendar year. (www.shrm.org)
Form 1099-NEC: In the context of 1099 tax filing, NEC stands for “Nonemployee Compensation” (the first letters of the three words None, Employee and Compensation). Most tax payers recognize NEC as box 7 on Form 1099-MISC. NEC is used to report income paid to independent-contractors / the-self-employed (referred to as 1099 employees for simplification purposes). So, while employers report income that gets paid to employees on Box 1 (Wages, tips, other compensation) of the W2 form, payers report income that gets paid to none-employees on Box 7 (NEC) of the 1099-MISC form. As an individual, if you received form 1099-MISC instead of Form W-2 then the payer did not consider you an employee and did not withhold income tax or social security and Medicare tax.
Form 1099-R: Form 1099-R is a tax form from the Internal Revenue Service (IRS) for reporting distributions from annuities, profit-sharing plans, retirement plans, IRAs, insurance contracts, or pensions.
Form 1099-S: A Form 1099-S is a tax document used to ensure that the full amount received for a real estate sale of some kind is accurately reported. A 1099-S can also be used to report income made on a rental property or investment property. For selling real estate, the buyer must complete and file their own 1099-S.
Form 8809: Use Form 8809 to request an initial or additional extension of time to file only the forms shown on line 6 for the current tax year.
Form W-2: Form W-2 is an Internal Revenue Service tax form used in the United States to report wages paid to employees and the taxes withheld from them. Employers must complete a Form W-2 for each employee to whom they pay a salary, wage, or other compensation as part of the employment relationship. - Wikipedia (https://en.wikipedia.org/)
Form W-9: Form W-9 (officially, the "Request for Taxpayer Identification Number and Certification") is used in the United States income tax system by a third party who must file an information return with the Internal Revenue Service (IRS). It requests the name, address, and taxpayer identification information of a taxpayer (in the form of a Social Security Number or Employer Identification Number). - Wikipedia (https://en.m.wikipedia.org/)
Gross Proceeds Payment: When a business sells an asset, whether tangible or intangible, it receives a payment, which is the gross proceeds. The amount includes the costs of production and other costs and expenses related to the transaction.
IRC Section 409A: Section 409A of the United States Internal Revenue Code regulates nonqualified deferred compensation paid by a "service recipient" to a "service provider" by generally imposing a 20% excise tax when a certain design or operational rules are contained in the section are violated.
IRC Section 6045: Every person doing business as a broker shall, when required by the Secretary, make a return, in accordance with such regulations as the Secretary may prescribe, showing the name and address of each customer, with such details regarding gross proceeds and such other information as the Secretary may by forms or regulations require with respect to such business.
IRS Notice 972CG: The IRS started mailing 972CG penalty notices in July 2013 regarding 1099's with missing or incorrect TIN/Name Combinations. A 972CG is a NOTICE OF PROPOSED CIVIL PENALTY. A simple way to prevent this costly penalty is to verify that your information is correct prior to filing.
Independent Contractor: An independent contractor is a person or entity contracted to perform work or provide services to another entity as a non-employee. As a result, independent contractors must pay their own Social Security and Medicare taxes. - Investopedia (https://www.investopedia.com/)
Information Returns Intake System (IRIS): The Information Returns Intake System (IRIS) Taxpayer Portal is a system that provides a no cost online. method for taxpayers to electronically file Form 1099 series. The Taxpayer Portal allows you to enter. data to create Forms 1099 by either keying in the information or uploading a .csv file.
Intangible Personal Property: Intangible personal property is an item of individual value that cannot be touched or held. Intangible personal property can include any item of worth that is not physical in nature but instead represents something else of value. Examples of intangible personal property include patents, copyrights, life insurance contracts, securities investments, and partnership interests.
Intellectual Property (IP): Intellectual property (IP) refers to creations of the mind, such as inventions, literary and artistic works, designs, and symbols, which are protected by law through exclusive rights granted to the owner for a limited time. The main types of IP protection are patents for inventions, copyrights for creative works, trademarks for brand identifiers, and trade secrets for confidential business information. IP rights serve to provide financial incentives for innovation, drive economic growth, and allow creators to control and benefit from their works.
Limited Liability Company (LLC): An LLC is a corporate structure where members cannot be held accountable for the company’s debts or liabilities. This can shield business owners from losing their entire life savings if, for example, someone were to sue the company. Can be a single member (much like a sole proprietor) or a multi-member. It shares certain traits of both corporations as well as partnerships or sole proprietorships. It is not a corporation.
Nonqualified Deferred Compensation (NQDC): A nonqualified deferred compensation (NQDC) plan is an elective or non-elective plan, agreement, method, or arrangement between an employer and an employee (or service recipient and service provider) to pay the employee or independent contractor compensation in the future. (www.irs.gov)
Overtime: Overtime is time and a half of what an employee earns for every hour worked over 40 in a workweek. The FLSA salary threshold is the minimum salary employers must pay employees for them to be exempt from overtime wages.
Personal Property: Personal property is something that you could pick up or move around. This includes such things as automobiles, trucks, money, stocks, bonds, furniture, clothing, bank accounts, money market funds, certificates of deposit, jewels, art, antiques, pensions, insurance, books, etc.
Real Property: Real property is land and any property attached directly to it, including any subset of land that has been improved through legal human actions. Examples of real properties can include buildings, ponds, canals, roads, and machinery, among other things
Reasonable Cause : Reasonable cause is based on all the facts and circumstances in your situation. The IRS will consider any reason which establishes that you used all ordinary business care and prudence to meet your federal tax obligations but were nevertheless unable to do so.
Sole Proprietor: A business that legally has no separate existence from its owner. The sole proprietorship is the simplest business form under which one can operate a business. The sole proprietorship is not a legal entity. It simply refers to a person who owns the business and is personally responsible for its debts.
TIN: A Taxpayer Identification Number is an identifying number used for tax purposes in the United States and in other countries under the Common Reporting Standard. In the United States, it is also known as a Tax Identification Number or Federal Taxpayer Identification Number.
TIN Match Program: TIN Matching is part of a suite of Internet-based pre-filing e-services that allows “authorized payers” the opportunity to match 1099 payee information against IRS records prior to filing information returns.
Tax Exempt Organization Search Tool: Tax Exempt Organization Search helps users find information about a tax-exempt organization’s federal tax status and filings.
Tax Gap: The gross tax gap is the difference between true tax liability for a given tax year and the amount that is paid on time. It is comprised of the nonfiling gap, the underreporting gap, and the underpayment (or remittance) gap.
Transmitter Control Code (TCC): The Transmitter Control Code (TCC) is an identifier that the IRS uses to distinguish different electronic filing companies. It's necessary when you need to file for a correction. Getting a TCC depends on how you file your 1099 forms
Vendor: A vendor is a person or business that supplies goods or services to a company. Another term for the vendor is the supplier. In many situations, a company presents the vendor with a purchase order stating the goods or services needed, the price, delivery date, and other terms.
This webinar received a total of 1 survey responses. Attendees have given an average rating of 4.0 stars out of a possible 5, reflecting the quality and value of the content presented.
Reviews From Webinar Survey
Our webinars are crafted to deliver exceptional value and insight to business professionals. Below, you'll find genuine feedback from attendees.